Water Damage, Sewer Backup and Overland Flood: What BC Home Insurance Covers
Burst pipes, sewer backup and overland flooding are three different claims in BC. See what a standard home, condo or tenant policy covers and which add-ons you need.
Updated October 26, 20268 min read
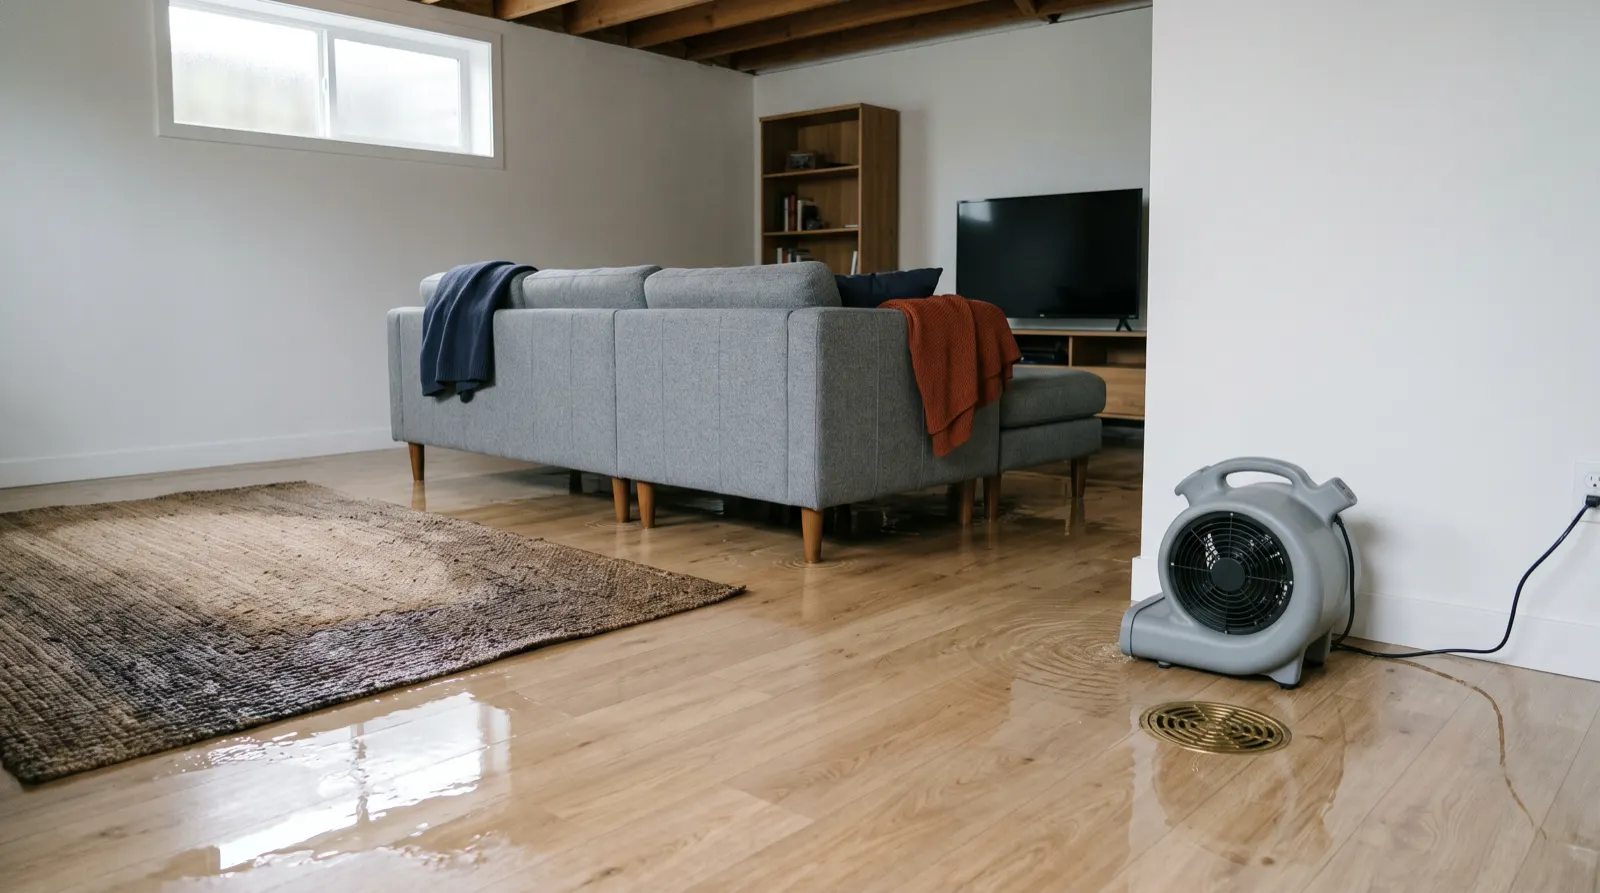
Most BC home insurance policies cover sudden and accidental water damage from inside the home, such as a burst pipe or a failed dishwasher hose, but they don't cover sewer backup or overland flooding unless you add those coverages. Gradual leaks, wear and tear and mould are generally excluded no matter what you add, and seepage or groundwater is usually excluded unless a specific optional coverage includes it. Which kind of water caused the damage is what decides a claim, so it's worth knowing which kinds your policy actually includes.
Key takeaways
- Water losses fall into three groups: sudden internal escape of water, sewer backup, and overland or surface water flooding. Each one is treated differently.
- On Bravo's home insurance policy, sudden and accidental internal water damage is part of the base coverage, while sewer backup and overland water are optional add-ons.
- Slow leaks, wear and tear and mould are generally not covered by any add-on, and seepage is usually excluded unless an optional coverage specifically includes it.
- Condo owners should check their strata's water deductible, and Bravo tenant policies carry a minimum $2,500 deductible for any water loss.
- In the first 24 hours after water damage, stop the source, document everything, limit further damage and report the claim.
Does home insurance cover water damage? It depends on the type
Where the water came from, and how fast it arrived, decide which part of the policy applies. The table shows the general pattern; your own wording and Cover Page are what count.
| Type of water loss | Typical example | Covered by base policy? | Add-on needed? |
|---|---|---|---|
| Sudden internal escape of water | Burst supply line, failed water heater, washing machine hose split | Usually yes | No |
| Sewer backup | Municipal sewer or drain backs up through a floor drain or toilet | Usually no | Yes, sewer backup coverage |
| Overland or surface water flood | Heavy rain or an overflowing creek enters at ground level | Usually no | Yes, overland flood (water protection) coverage |
| Gradual leak or seepage | Slow drip under a sink, water seeping through a foundation crack | No | Gradual leaks: no. Seepage: only if an optional coverage includes it |
| Wear and tear, mould, rot | Aging roof, corroded pipe, mould from long-term humidity | No | Not available as an add-on |
What counts as sudden and accidental water damage?
This is the core water coverage on a home policy. It's meant for water that escapes suddenly from plumbing, heating or sprinkler systems, or from a household appliance, such as a pipe bursting in a wall or a water heater failing.
Bravo's home insurance policy is designed to cover sudden and accidental internal water damage to the dwelling and your contents. The damage usually has to be sudden. A pipe that has been dripping inside a wall for months is generally treated as gradual damage, even if you only just found it.
Is sewer backup covered by home insurance?
Not by default. Sewer backup happens when water and waste come back up through floor drains, toilets or sump pits, often because a municipal system is overwhelmed during heavy rain. Homes with basements and basement suites are most exposed.
On a Bravo home policy, sewer backup coverage is an optional add-on. On a Bravo tenant policy, the optional Sewer Back Up Coverage extends to water backing up from a sewer, sump, septic tank, or an eavestrough connected to the sewer. If you have a finished basement or rent out a suite, ask about it before you need it.
Does home insurance cover overland flooding in BC?
Overland flood means water entering the home at ground level from outside, such as heavy rain, rising rivers or creeks, or snowmelt running across the surface. Most standard BC home policies exclude it unless you add overland flood coverage.
BC's coast is well known for atmospheric rivers. In November 2021, atmospheric river storms caused severe flooding in the Fraser Valley, including the Sumas Prairie area of Abbotsford, and damaged highways across southern BC. Events like that are exactly what overland flood coverage is for.
Bravo's home policy offers overland water as an optional add-on. On Bravo's tenant policy, the optional Water Protection Coverage is designed for flood, surface water and certain ground water caused by extreme weather. If your home is near a river, creek or low-lying farmland, ask your broker what overland coverage is available for your address.
What water damage is almost never covered?
Some water losses are excluded whatever add-ons you have:
- Gradual leaks and seepage: slow drips, water seeping through foundations or around windows over time. Some optional overland or groundwater coverages include certain seepage, so check your wording.
- Wear and tear: aging roofs, corroded pipes, failed caulking and other maintenance problems.
- Mould and fungi: Bravo's tenant policy specifically excludes mould, and many policies limit or exclude it.
- Freezing while you're away: Bravo's tenant policy excludes freezing damage while the home is unoccupied for more than 10 consecutive days in heating season, unless the water was shut off, someone checked the home daily, or low-temperature monitoring was in place.
Insurance is built for sudden, unexpected events, not upkeep.
Water damage for condo owners and renters
Condo owners. The strata's master policy covers the building, but when a water loss starts in your unit, the strata may be able to recover its deductible from you, even if you weren't negligent. BC strata deductibles have climbed sharply and can range from $100,000 to $750,000 or more, and the loss-assessment limit on a base policy is often lower than that. Bravo's condo insurance includes water damage coverage (overland, sewer and burst pipes) with deductible options, and the Strata Water Deductible add-on is designed to cover your share of the strata's water deductible when you're assessed. It typically costs $50–$150 a year depending on the deductible level. For how strata deductibles work, read our guide to strata insurance deductibles in BC.
Renters. Bravo's tenant insurance covers your belongings, not the building. The minimum deductible for any water loss is $2,500 unless your Cover Page shows a higher amount. Flood and sewer backup are excluded by default but can be added as options, which matters if you live in a basement suite.
What to do in the first 24 hours after water damage
- Stop the source. Turn off the main water shut-off or the valve for the fixture that failed. If water is near outlets or the electrical panel, keep clear and call an electrician or the utility.
- Document everything. Take photos and video of the water, the source and damaged items before you move anything. Keep damaged items until you're told you can discard them. Sewer water can carry contaminants, so avoid direct contact.
- Prevent further damage. Move belongings to dry areas, mop up standing water and run fans or dehumidifiers. BC's statutory conditions require you to take reasonable steps to prevent further loss or damage.
- Report it promptly. Contact your broker or follow the steps on our claims page. Keep receipts for emergency repairs, drying equipment and any hotel stay.
How to lower your water damage risk
A few practical steps reduce the chance and size of a water loss:
- Know where your main shut-off is and make sure everyone at home can turn it.
- Install a backwater valve on the pipe that connects your home to the sewer to help stop sewage from backing up into the basement. A permit may be required and some municipalities offer rebates, so check locally and use a licensed plumber.
- Maintain your sump pump. Test it before the fall rain season and consider a battery backup.
- Add leak detectors or an automatic shut-off valve near water heaters, washing machines and under sinks.
- Replace aging hoses and supply lines. Braided steel lines are more durable than rubber.
- Keep gutters and downspouts clear and direct water away from the foundation.
If you've made any of these upgrades, mention them when you talk to a Bravo broker about sewer backup or overland coverage.
Frequently asked questions
Does home insurance cover a burst pipe?
Usually, if the pipe burst suddenly and accidentally. On Bravo's home policy, sudden and accidental internal water damage is part of the base coverage. A long-term slow leak is treated as gradual damage, and freezing in an empty home can be excluded if the required precautions weren't taken, so check your policy wording.
What is the difference between sewer backup and overland flood coverage?
Sewer backup covers water that comes up through your drains, toilets or sump from the sewer system. Overland flood covers water that enters from outside at ground level, such as rain runoff or an overflowing river. They are separate add-ons, and a home in a flood-prone area may need both.
Is water damage in a basement suite covered?
It depends on the source. Sudden internal escape of water falls under a home policy's base water coverage, but sewer backup and overland flood need add-ons, and the tenant's belongings need their own tenant policy. Bravo's tenant policy excludes water below ground level unless it comes from a pool, fire-fighting or a public watermain, or an optional water coverage applies.
Will a water damage claim affect my premium?
Claims history is one of the factors that affects home insurance premiums in BC. A water claim can affect your future pricing or the terms you're offered. A Bravo broker can help you weigh whether a small loss is worth claiming against your deductible.
Does condo insurance cover my strata's water deductible?
Your base condo policy may include some loss-assessment coverage, but the limit is often lower than the strata's water deductible. Bravo's Strata Water Deductible add-on is designed to cover your share when you're assessed, and it stacks with the loss-assessment coverage on your base policy.
This guide is general information, not advice. What a policy covers is set by its wording, declarations and endorsements, and varies by insurer. Talk to a licensed broker about your situation before you buy or change coverage.
More residential guides
What Does Tenant Insurance Cover in BC? A Plain-English Breakdown
Your belongings, worldwide liability, living costs after a fire or evacuation, and the limits that catch renters out. A plain-English guide to BC tenant insurance.
Read the guide
Replacement Cost vs Actual Cash Value: How BC Home Insurance Pays a Claim
Actual cash value, replacement cost and guaranteed rebuild pay out very differently after a claim. Worked examples for BC homeowners, condo owners and renters.
Read the guide
Strata Insurance Deductibles in BC: What Condo Owners Pay and How to Protect Yourself
How BC strata water and earthquake deductibles get charged back to owners, and how loss assessment and deductible add-ons on your condo policy close the gap.
Read the guideGet covered without the runaround.
Compare your options, get a quote, or talk to a licensed BC advisor when you want a second opinion.